Value and Behavioral Accounting

Value and Behavioral Accounting

Journal  of Value and Behavioral Accounting

 Print ISSN: 2476-7166
Online ISSN:2538-4228

دسترسی آزاد

Access to articles from this site is free

The journal of "Iranian journal of Value & Behavioral Accounting” is a research-scientific journal which publishes research-scientific papers in the field of Value and behavioral Accounting and Auditing with the aim of developing  knowledge in the following issues:
  • Environmental Accounting, auditing and reporting, social responsibility, accountability (financial and operational) and sustainability
  • Behavioral Accounting (including professional judgment, cultural and psychological issues)
  • Ethical issues in accounting and auditing (including ethics, ethics education, forensic accounting, fraud and corruption, etc.)
  • Islamic Accounting and auditing

 The submitted papers will be published after special review as well as the approval of the editorial board. The proprietors of this journal are the Faculty of financial sciences of Kharzmi University and Iranian Management Accounting Association. The honorable professors and researchers are highly appreciated if they visit this site, register, submit and set up their papers based on guidelines. Therefore, visiting in person or calling the journal office are not recommended, so all connections with authors and honorable reviewers are done through the site. 

  • Average review time of articles: 6 Weeks
  • Frequency:semiannually
  • Review type: Reviews and authors cannot see each other's attributes;(Double Blind)
  • COPE: This publication complies with the COPE Code of Ethics;
  • Language: Bilingual: Persian (abstract and sources of English articles)
  •  Plagiarism: Several light software is used to prevent plagiarism ;(hamanandjoo)
  • charge fees for publishing an article (APCs): Free
  • The cost of arbitration: Free
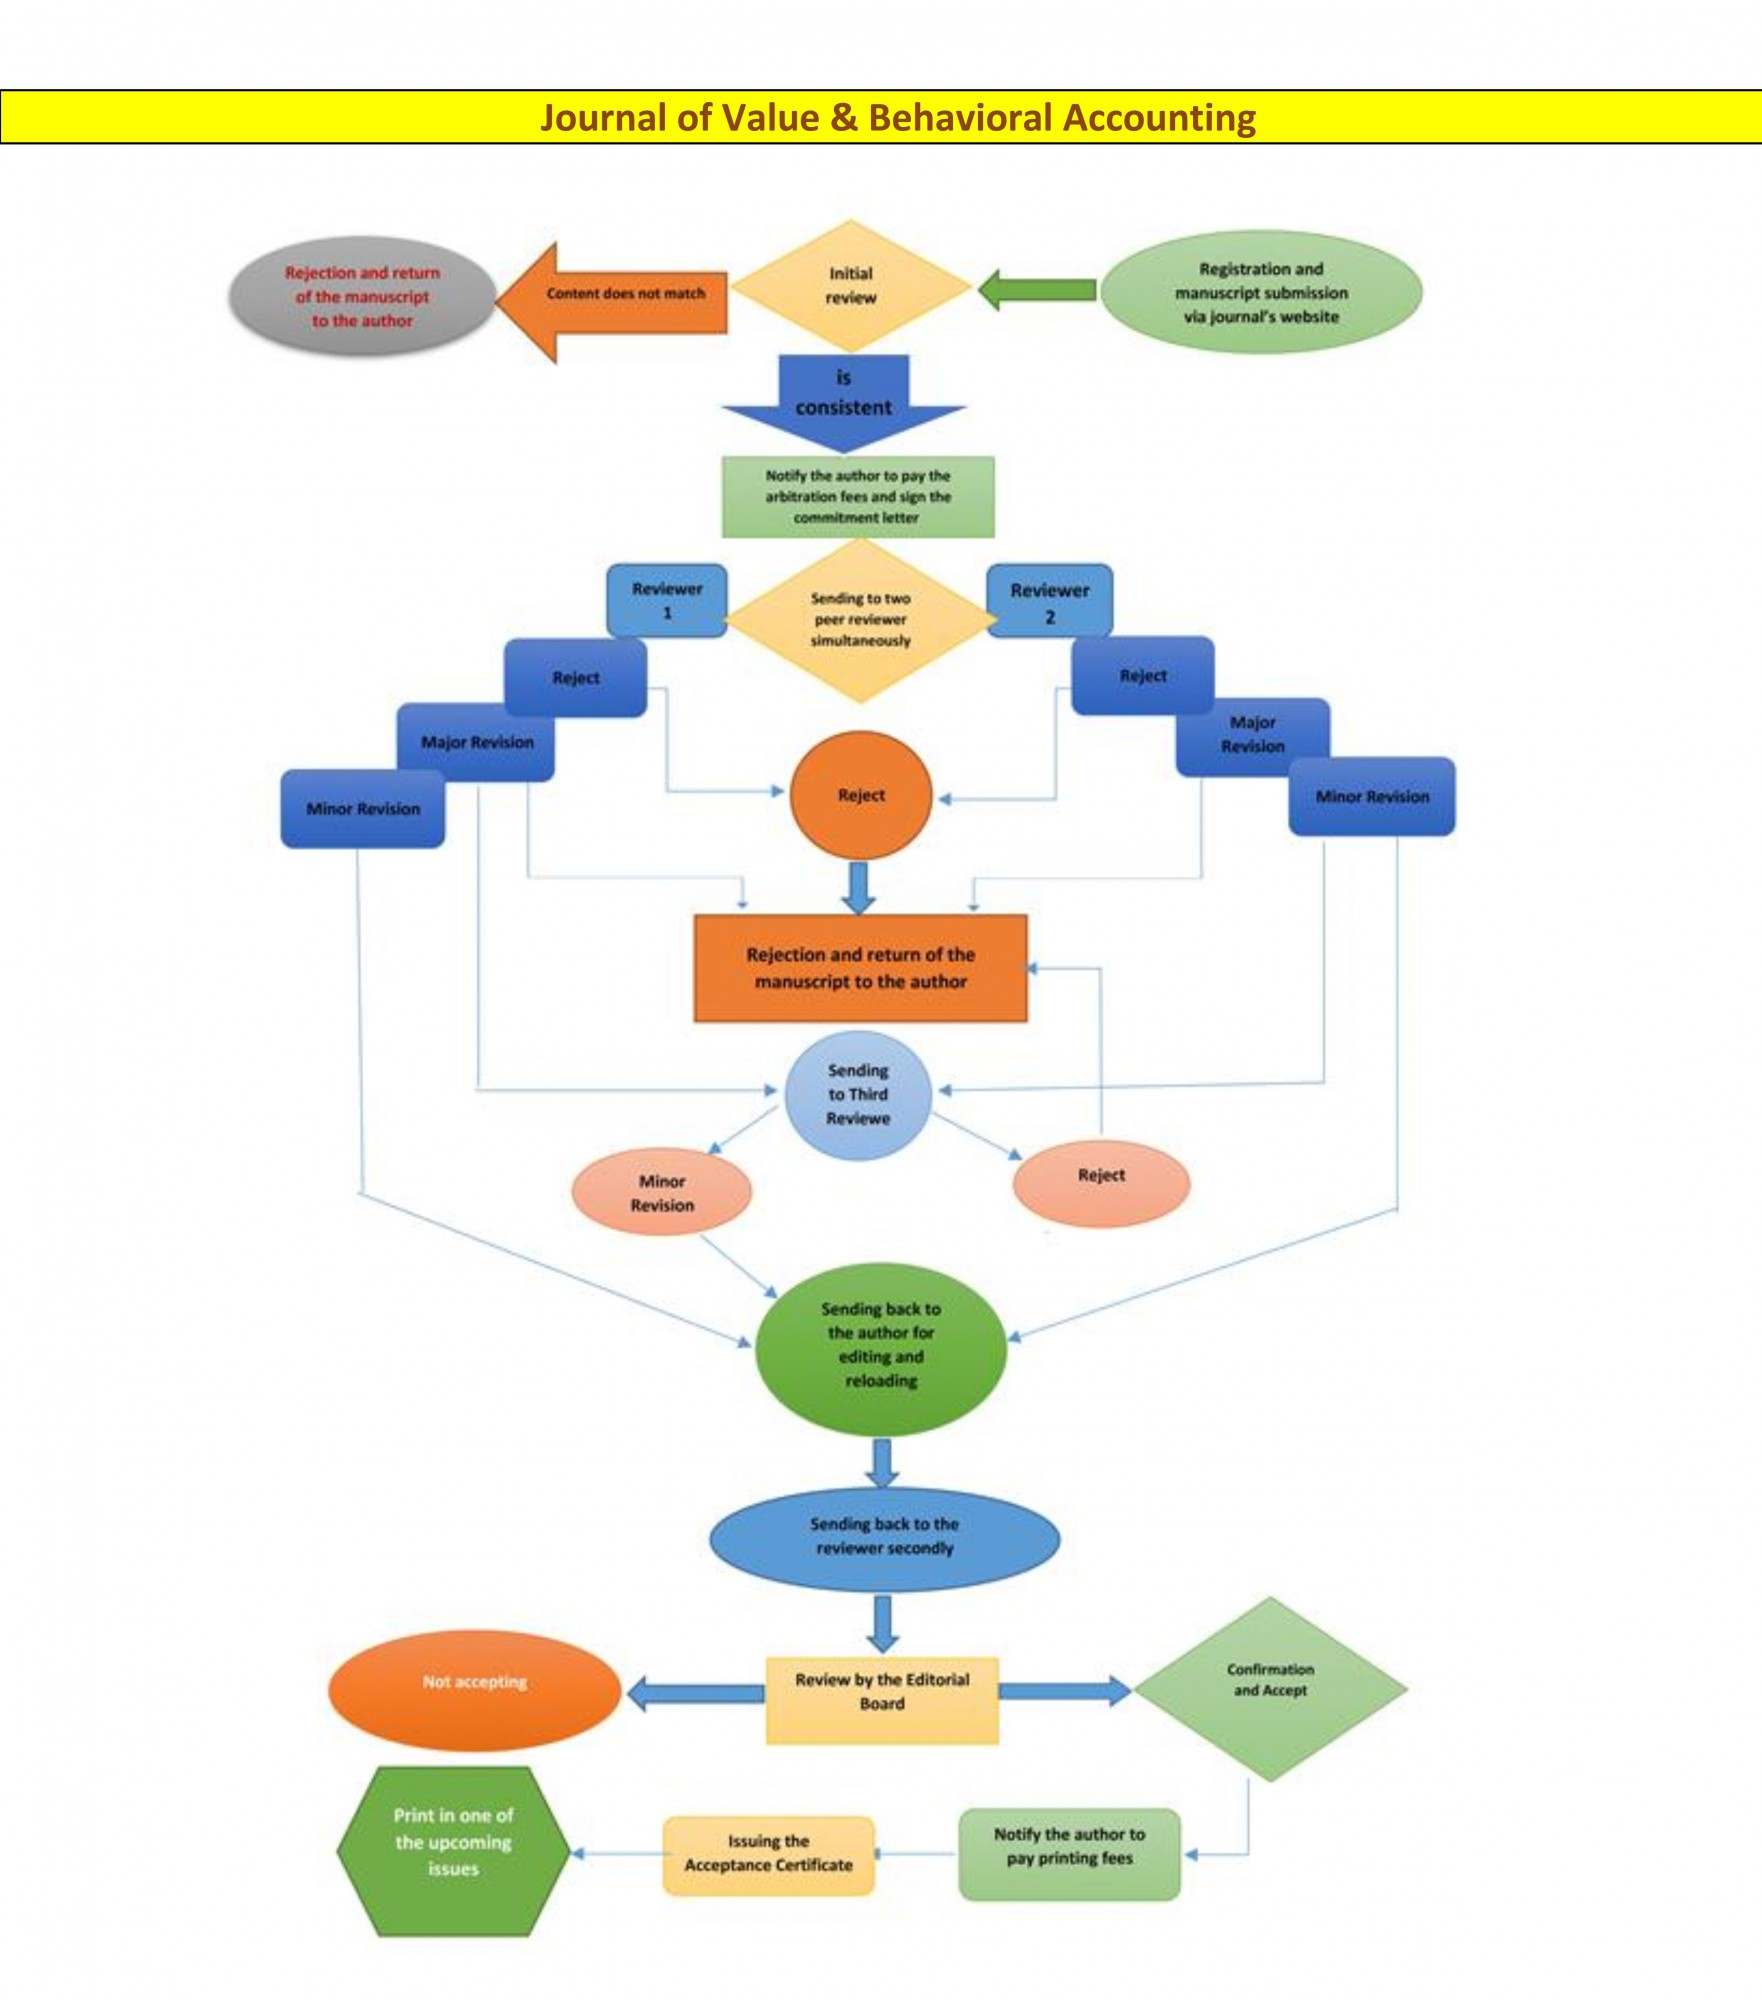
  • Diagram of the Acceptance Process in journal of Value & Behavioral Accounting
  • Copyright: Journal allows the author(s) to hold the copyright without restrictions. 
  • CC BY-NC-ND 
    This license allows others to download the works and share them with others as long as they credit them, but they can’t change them in any way or use them commercially.


Current Issue: Volume 10, Issue 20, September 2025 

Keywords Cloud

  • Corporate social responsibility
  • professional skepticism
  • Auditing
  • professional ethics
  • Auditors
  • Forensic accounting
  • machiavellianism
  • Accounting
  • Theory of Planned Behavior
  • Fraud
  • Grounded theory
  • Social responsibility
  • Corporate Governance
  • Audit Quality
  • Thematic analysis
  • Audit
  • Professional judgment
  • Information Asymmetry
  • Auditor
  • Whistleblowing
  • Environmental Reporting
  • Earnings management
  • Sustainability Reporting
  • professional commitment
  • Locus of control
  • Fraud Risk Assessment
  • Meta-synthesis
  • Signaling Theory
  • behavioral accounting
  • Tax Avoidance
  • Iran
  • Content analysis
  • professional identity
  • Financial reporting
  • Stock Price Crash Risk
  • Scenario Planning
  • Islamic accounting
  • Financial Performance
  • sustainable development
  • Asymmetric cost behavior
  • role ambiguity
  • job performance
  • Firm Value
  • Decision making
  • Cognitive dissonance
  • Iranian Association of Certified Public Accountants
  • Social identity theory
  • Accountability
  • Ethics
  • Accounting Students
  • Islamic Financial Reporting
  • Psychological well-being
  • Auditor Judgment
  • Audit profession
  • Ethical accounting decision making
  • Theme Analysis
  • Firm performance
  • Internal Audit
  • managers\' overconfidence
  • Religious Beliefs
  • Auditing profession
  • Organizational Identity
  • Corporate Culture
  • Subjective norms
  • Social capital
  • Cost of equity
  • tax evasion
  • stress
  • Financial Reporting Quality
  • Readability of financial reporting
  • Emotional Intelligence
  • Whistle Blowing
  • Financial Managers
  • Managerial Ability
  • Social Dominance
  • Organizational Citizenship Behavior
  • Ethical leadership
  • Systematic Risk
  • Accruals
  • Stakeholders
  • Motivation
  • self-efficacy
  • Cost stickiness
  • Social status
  • Audit Committee
  • professional performance
  • Fraudulent Financial Reporting
  • Future Study
  • Meta-analysis
  • Social Trust
  • Family firms
  • Greenwashing
  • Reporting
  • Corporate sustainability
  • Personal Moral Philosophy
  • Fraud Triangle
  • Corporate Social Responsibility (CSR)
  • modesty
  • behavioral biases
  • Perceptual Justice
  • Board Expertise
  • Behavioral Characteristics of the Company
  • Machiavellian ism
  • Social Ethics
  • Managers\' Myopia‌
  • Social Pressure Anomie
  • Financial Transparency
  • Involvement
  • Behavioral Commitment
  • Metacognition
  • Linear and Nonlinear Brain Functions
  • corporate governance.corporate sustainability accounting
  • Behavioral Features and Auditor
  • curriculum
  • Audit effort
  • Unsystematic Risk
  • Investment Intentions
  • Number of Total Restriction Paragraph
  • Fuzzy Delphi
  • Unethical Reporting
  • Labor Quality
  • Gender diversity of auditors
  • faith theory
  • Fraud Pentagon Model
  • Perception of Fairness and Whistle-blowing
  • Selective attention
  • Individual Risk-taking
  • social networks analysis
  • anomaly detection
  • Sustainability
  • Form of Financial Iinformation Presentation
  • Professional Skeptics Auditors
  • Socio-Emotional Wealth Perspective
  • Working Capital Adjustment Rate
  • continuous learning
  • key audit matters
  • Youth Religious Behavior
  • Agency theory
  • Trait Professional skepticism
  • Individual Mechanisms
  • Mixed Methods (Quantitative and Qualitative Methods)
  • Individual Morality
  • financial leverage
  • Scandal
  • selective information disclosure
  • symbolic behavior
  • Ethics Real Earnings Management
  • Metasynthesis
  • Ownership of Board Members
  • Managers\' Cash Bonus
  • Neutrality
  • Spoken Interaction
  • Government Ownership
  • Social Factors
  • Sociolinguistics
  • citizenship behavior
  • Stock price informativeness
  • Philosophic - Mindedness
  • formal surveillance
  • Auditor Gender
  • Earning Management
  • Audit Fee Dependence
  • formal sanctions
  • Professional Socialization
  • Auditors Working in Auditing Organization
  • Saw Method
  • Certified Tax Advisors
  • Non-Paternal Behavior
  • Reading Patterns
  • Return on Assets
  • Income Tax
  • Conditional Conservatism
  • Propensity to Cheat
  • board members
  • Performance Capability
  • technology acceptance
  • Analytic Hierarchy Process (AHP)
  • external source of control
  • external transparency
  • Rules-Based Accounting
  • Moral Outrage
  • Neo Big Five Traits
  • Professional Skepticism (PS)
  • Individual Organizational Behavior
  • future research
  • Ethical Decision-making of Accountants
  • Perceived Moral Intensity
  • Topics in Environmental Biology
  • Obedience Pressure
  • Perceived Partner Support
  • Environmental and Social and Corporate Governance Reporting (ESG)
  • International Study
  • Importance-Performance Analysis
  • Bystander Effect
  • Earnings Manipulation
  • Supreme Audit Court
  • Performance of Iranian Audit firms
  • Ethical Predispositions
  • Creative Corporate Culture
  • Auditor Characteristics