Value and Behavioral Accounting

Value and Behavioral Accounting

Journal  of Value and Behavioral Accounting

 Print ISSN: 2476-7166
Online ISSN:2538-4228

دسترسی آزاد

Access to articles from this site is free

The journal of "Iranian journal of Value & Behavioral Accounting” is a research-scientific journal which publishes research-scientific papers in the field of Value and behavioral Accounting and Auditing with the aim of developing  knowledge in the following issues:
  • Environmental Accounting, auditing and reporting, social responsibility, accountability (financial and operational) and sustainability
  • Behavioral Accounting (including professional judgment, cultural and psychological issues)
  • Ethical issues in accounting and auditing (including ethics, ethics education, forensic accounting, fraud and corruption, etc.)
  • Islamic Accounting and auditing

 The submitted papers will be published after special review as well as the approval of the editorial board. The proprietors of this journal are the Faculty of financial sciences of Kharzmi University and Iranian Management Accounting Association. The honorable professors and researchers are highly appreciated if they visit this site, register, submit and set up their papers based on guidelines. Therefore, visiting in person or calling the journal office are not recommended, so all connections with authors and honorable reviewers are done through the site. 

  • Average review time of articles: 6 Weeks
  • Frequency:semiannually
  • Review type: Reviews and authors cannot see each other's attributes;(Double Blind)
  • COPE: This publication complies with the COPE Code of Ethics;
  • Language: Bilingual: Persian (abstract and sources of English articles)
  •  Plagiarism: Several light software is used to prevent plagiarism ;(hamanandjoo)
  • charge fees for publishing an article (APCs): Free
  • The cost of arbitration: Free
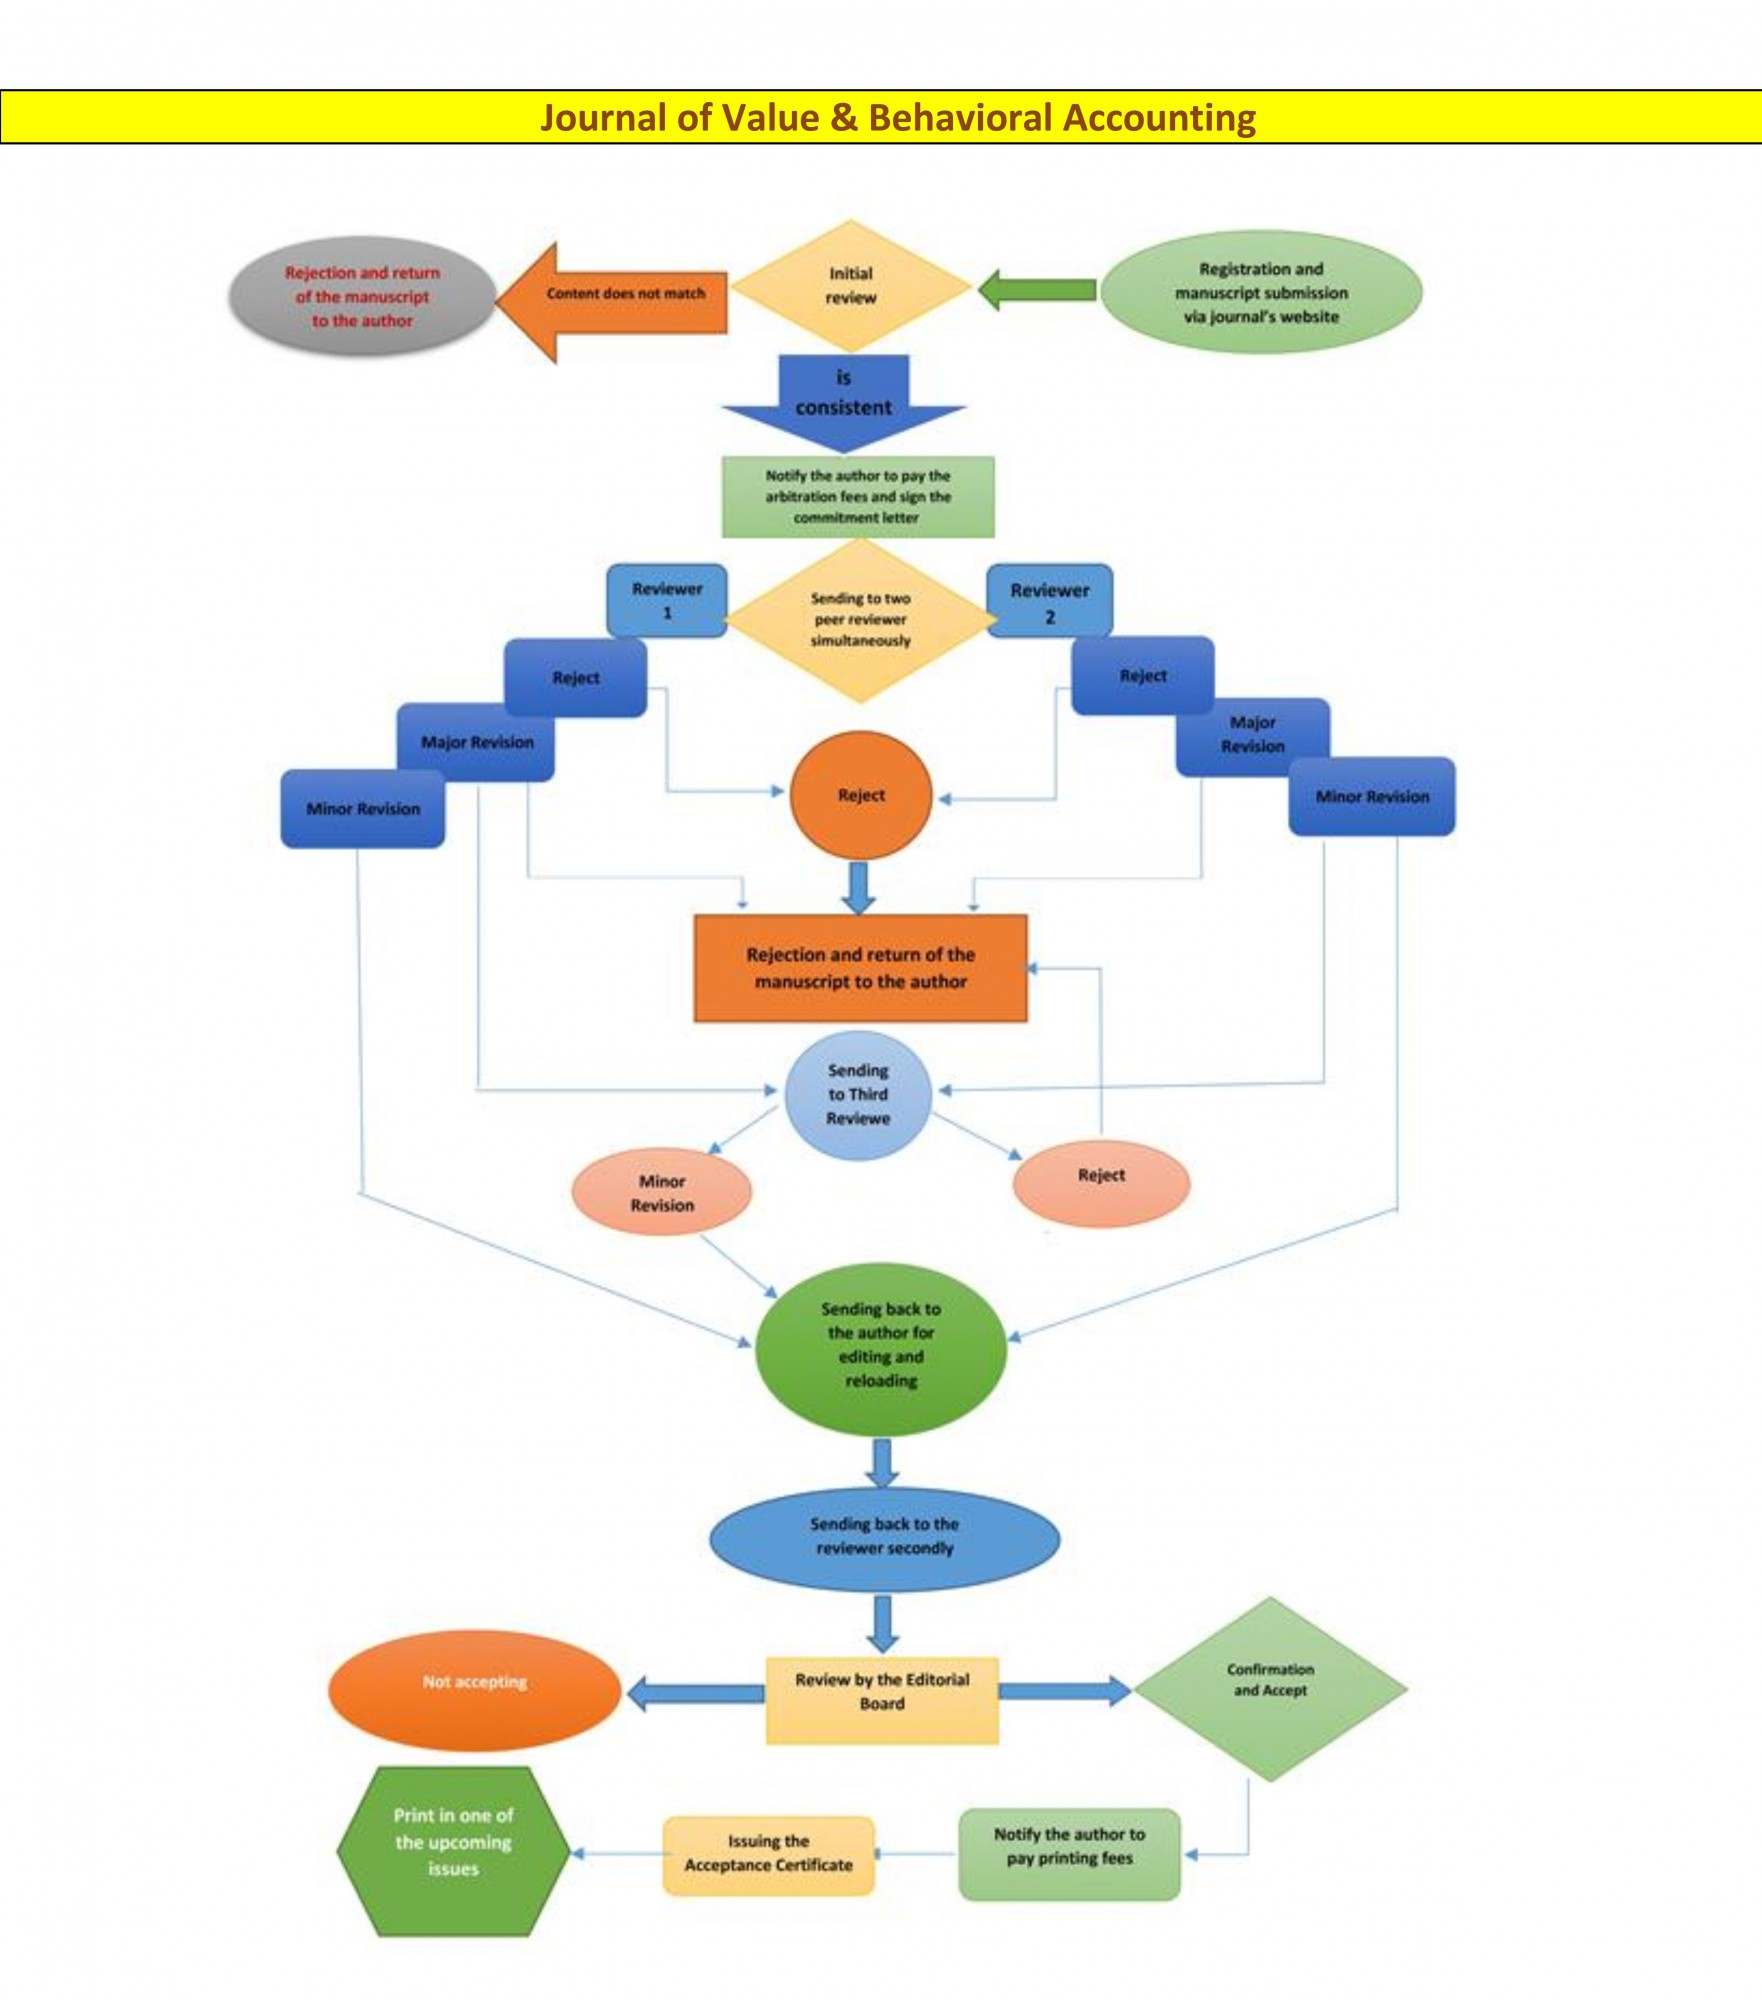
  • Diagram of the Acceptance Process in journal of Value & Behavioral Accounting
  • Copyright: Journal allows the author(s) to hold the copyright without restrictions. 
  • CC BY-NC-ND 
    This license allows others to download the works and share them with others as long as they credit them, but they can’t change them in any way or use them commercially.


Current Issue: Volume 10, Issue 20, September 2025 

Keywords Cloud

  • Corporate social responsibility
  • professional skepticism
  • Auditing
  • professional ethics
  • Auditors
  • machiavellianism
  • Theory of Planned Behavior
  • Forensic accounting
  • Accounting
  • Fraud
  • Grounded theory
  • Corporate Governance
  • Thematic analysis
  • Social responsibility
  • Audit Quality
  • Audit
  • Information Asymmetry
  • Professional judgment
  • Auditor
  • Whistleblowing
  • Locus of control
  • Earnings management
  • Sustainability Reporting
  • professional commitment
  • Environmental Reporting
  • Fraud Risk Assessment
  • Meta-synthesis
  • Signaling Theory
  • behavioral accounting
  • Tax Avoidance
  • Content analysis
  • Islamic accounting
  • professional identity
  • Iran
  • Financial reporting
  • Scenario Planning
  • Stock Price Crash Risk
  • Financial Performance
  • sustainable development
  • Asymmetric cost behavior
  • role ambiguity
  • job performance
  • Firm Value
  • Personal Moral Philosophy
  • Cognitive dissonance
  • Iranian Association of Certified Public Accountants
  • Social identity theory
  • Accountability
  • Subjective norms
  • Accounting Students
  • Ethics
  • Social Dominance
  • Auditor Judgment
  • Audit profession
  • professional performance
  • Ethical accounting decision making
  • Theme Analysis
  • Firm performance
  • Internal Audit
  • managers\' overconfidence
  • Religious Beliefs
  • Auditing profession
  • Organizational Identity
  • Corporate Culture
  • Organizational Citizenship Behavior
  • Social capital
  • Cost of equity
  • tax evasion
  • stress
  • Financial Reporting Quality
  • Readability of financial reporting
  • Whistle Blowing
  • Financial Managers
  • Emotional Intelligence
  • Managerial Ability
  • Decision making
  • Ethical leadership
  • Systematic Risk
  • Accruals
  • Stakeholders
  • Motivation
  • self-efficacy
  • Cost stickiness
  • Social status
  • Audit Committee
  • Islamic Financial Reporting
  • Psychological well-being
  • Future Study
  • Fraudulent Financial Reporting
  • Social Trust
  • Family firms
  • Greenwashing
  • Reporting
  • Corporate sustainability
  • Meta-analysis
  • Fraud Triangle
  • Corporate Social Responsibility (CSR)
  • modesty
  • behavioral biases
  • Perceptual Justice
  • Board Expertise
  • Unethical Reporting
  • Machiavellian ism
  • Social Ethics
  • Managers\' Myopia‌
  • Social Pressure Anomie
  • Financial Transparency
  • Involvement
  • Behavioral Commitment
  • Metacognition
  • Linear and Nonlinear Brain Functions
  • corporate governance.corporate sustainability accounting
  • Behavioral Features and Auditor
  • Audit effort
  • Unsystematic Risk
  • Investment Intentions
  • Number of Total Restriction Paragraph
  • Behavioral Characteristics of the Company
  • Fuzzy Delphi
  • Labor Quality
  • Gender diversity of auditors
  • faith theory
  • Fraud Pentagon Model
  • Perception of Fairness and Whistle-blowing
  • Selective attention
  • organizational performance
  • Individual Risk-taking
  • social networks analysis
  • anomaly detection
  • Sustainability
  • Form of Financial Iinformation Presentation
  • Professional Skeptics Auditors
  • Socio-Emotional Wealth Perspective
  • Working Capital Adjustment Rate
  • continuous learning
  • key audit matters
  • Youth Religious Behavior
  • Agency theory
  • Trait Professional skepticism
  • Individual Mechanisms
  • Mixed Methods (Quantitative and Qualitative Methods)
  • Individual Morality
  • financial leverage
  • Supreme Audit Court
  • selective information disclosure
  • symbolic behavior
  • Ethics Real Earnings Management
  • Metasynthesis
  • Ownership of Board Members
  • Managers\' Cash Bonus
  • Neutrality
  • Spoken Interaction
  • Perceived Partner Support
  • Social Factors
  • Sociolinguistics
  • Ethical Decision-making of Accountants
  • Stock price informativeness
  • Philosophic - Mindedness
  • formal surveillance
  • Auditor Gender
  • Earning Management
  • Audit Fee Dependence
  • formal sanctions
  • Professional Socialization
  • Auditors Working in Auditing Organization
  • Saw Method
  • Certified Tax Advisors
  • board members
  • Non-Paternal Behavior
  • Reading Patterns
  • Income Tax
  • Conditional Conservatism
  • Return on Assets
  • Performance Capability
  • Propensity to Cheat
  • Analytic Hierarchy Process (AHP)
  • external source of control
  • external transparency
  • Rules-Based Accounting
  • Moral Outrage
  • technology acceptance
  • Professional Skepticism (PS)
  • Neo Big Five Traits
  • citizenship behavior
  • future research
  • Perceived Moral Intensity
  • Topics in Environmental Biology
  • Government Ownership
  • Obedience Pressure
  • Environmental and Social and Corporate Governance Reporting (ESG)
  • International Study
  • Importance-Performance Analysis
  • Bystander Effect
  • Scandal
  • Individual Organizational Behavior
  • Performance of Iranian Audit firms
  • Ethical Predispositions
  • Creative Corporate Culture
  • Audit report
  • Earnings Manipulation